
• Skip to primary navigation
  • Skip to main content
  • Skip to primary sidebar

Income Tax Aid

  • Home
  • About/Contact
  • Income Tax News

Income Tax News

West Virginia Just Changed Its Social Security Tax Rules – Is Your State Next?

July 6, 2026 by

If you collect Social Security and you live in West Virginia, January 1, 2026
was a meaningful milestone: the Mountain State officially stopped taxing your senior benefits.

The change caps a three-year phaseout that began in 2024, when West Virginia
allowed retirees to deduct 35% of their Social Security income from state taxes.
That deduction jumped to 65% in 2025, then hit 100% in 2026 — meaning the tax is
fully gone. You won’t feel the full effect until you file your 2026 return in
2027, but for West Virginia’s retirees, the math is simple: a benefit that was
taxed at the state level no longer is, regardless of income.

West Virginia’s decision didn’t happen in isolation. It’s part of a broader and
accelerating trend: states steadily eliminating a tax that many retirees — and
legislators — view as double taxation, since Social Security benefits are
already partially taxed at the federal level.

Find Out: I can’t believe this $24,108 Social Security secret was so simple

Where the map stands today

With West Virginia’s change, only eight states now tax Social Security benefits
to any degree: Colorado, Connecticut, Minnesota, Montana, New Mexico, Rhode
Island, Utah, and Vermont. That’s down significantly from just a decade ago,
when the number was nearly double that. No state has gone the other direction
and adopted a new Social Security tax.

Three factors tend to separate states that have eliminated the tax from those
that haven’t. Political will is the clearest: West Virginia’s phaseout passed
with strong bipartisan support, backed by Governor Jim Justice and championed by
AARP.

Budget conditions matter just as much — West Virginia was able to absorb a
roughly $37 million revenue reduction; states where full elimination would cost
hundreds of millions face a harder calculation.

And competitive pressure is real: as more states drop the tax, those that keep
it risk losing retirees — and the spending they bring — to friendlier neighbors.

Shopping for cheaper auto insurance? Enter your zip code here to get started.

Vermont and Utah loosened rules in 2025

Two of the remaining eight states moved to ease their Social Security taxes in
2025, though neither went all the way to elimination.

Vermont enacted legislation raising the income thresholds at which Social
Security benefits qualify for the state’s full exemption, increasing the cutoff
from $50,000 to $55,000 for single filers and from $65,000 to $70,000 for joint
filers, effective for 2025 tax years. A more sweeping bipartisan proposal —
which would have phased out Vermont’s Social Security tax entirely over eight
years — was introduced in the legislature but did not advance.

Utah signed legislation raising the income thresholds at which its Social
Security tax credit begins to phase out. Governor Spencer Cox signed the bill in
2025, bumping the single filer threshold from $45,000 to $54,000 and the joint
filer threshold from $75,000 to $90,000 — a 20% increase across the board. The
change costs the state approximately $24 million and benefits an estimated
88,800 Utahns, saving them an average of $257 per year.

Why other states haven’t eliminated the tax yet

Legislators in all eight remaining states introduced bills in 2025 to reduce or
eliminate the Social Security tax. Most stalled. Montana’s attempted full repeal
failed outright, and the state also rolled back some existing deductions during
the same session. Minnesota’s legislature considered elimination, but the
estimated cost — nearly $400 million per year — proved prohibitive, and those
bills died in committee. Connecticut introduced legislation to widen its
existing exemption; it was referred to committee and did not advance.

That pattern is worth noting: none of the eight states moved backward, and all
of them saw active legislative proposals. Lawmakers who came up short in 2025
are expected to reintroduce bills in coming sessions, particularly as the
political salience of Social Security grows.

Save Money: Things to cut when living on retirement (many people ignore #11)

What this means for your tax bill

If you live in one of the eight states that still tax Social Security benefits,
your actual exposure depends heavily on your income. Most of these states use
income thresholds or phaseouts that exempt lower earners entirely.

Colorado, for example, allows taxpayers 65 and older to deduct all their
federally taxed Social Security income from state taxes.

Connecticut fully exempts benefits for single filers with adjusted gross income
below $75,000 and joint filers below $100,000 — and applies a 75% exemption
above those limits, so only 25% of benefits may be taxed for higher earners.

The trend is clearly toward elimination. But timing and income thresholds vary
significantly by state, and this is an area where laws have been changing
quickly. Before assuming your state’s rules haven’t shifted, check directly with
your state’s department of revenue or a current tax resource — what applied last
year may already be outdated.

Bottom line

West Virginia’s completed phaseout is the clearest recent proof that eliminating
the state Social Security tax is politically achievable — even in a state with
tight budget margins.

The remaining eight states aren’t ignoring the pressure; they’re feeling it.
Vermont and Utah have already moved the goalposts, and legislators across the
holdouts introduced bills in 2025 that didn’t pass but aren’t going away.

The question for retirees in Colorado, Connecticut, Minnesota, Montana, New
Mexico, Rhode Island, Utah, and Vermont isn’t really if their state
will act — it’s when, and whether the income thresholds will cover them when it
does. For now, the smartest move is to know exactly where your state stands so
you can factor that into your retirement
plan.

More from FinanceBuzz:
Originally Appeared Here

Filed Under: Income Tax News

A 73-Year-Old Feared Her RMD Would Drain Her IRA and Tax Her Social Security. The IRS Formula Is Built So It Won’t.

July 3, 2026 by

© shurkin_son / Shutterstock.com

She turned 73 this year, and her IRA custodian’s letter arrived with weight. Her first required minimum distribution (RMD) is due, and weeks of back-of-the-envelope math keep showing the same result: forced withdrawals will drain her traditional IRA, and the extra income will drag more of her Social Security into taxable territory. Online forum threads from new retirees in their first RMD year read identically, with a recurring worry that the IRS has rigged the rules to empty the account.

The reassurance is hiding in plain sight, written into the IRS Uniform Lifetime Table itself. The data is built on an assumption that makes the required withdrawal smaller than most people expect, and that single design choice softens the tax hit on her Social Security.

The Divisor Assumes a Younger Beneficiary

The Uniform Lifetime Table calculates her required withdrawal as if her IRA had a beneficiary exactly 10 years younger than she is. There is no such person required. The IRS bakes that assumption into the math, which stretches the schedule out. At age 73, the divisor is roughly 26.5, which works out to a required withdrawal of about 3.8% of her December 31 balance.

Compare that with the Social Security Administration’s (SSA’s) actuarial tables, which put a 73-year-old’s remaining life expectancy in the 13 to 15 year range. If the IRS used her real life expectancy, the required percentage would be nearly double. Instead, the rule is structurally generous. The account is meant to last.

The percentage climbs with age. By 80, the required withdrawal rises to roughly 5% of the balance, and by 85 it is closer to 6%. Even at those ages, the math is gentler than her actual lifetime would justify. A balance earning a reasonable return through her 70s can still grow in dollar terms, even as she takes the required amount each year.

Why a Smaller Withdrawal Means Less Tax on Her Benefit

Social Security taxation works on a sliding scale tied to combined income, which is roughly adjusted gross income (AGI) plus any tax-exempt interest plus half of her Social Security. Once combined income crosses certain thresholds, a portion of her benefit becomes taxable, with up to 85% of the benefit potentially subject to ordinary income tax. That 85% refers to the share of the benefit added to taxable income, which is then taxed at her ordinary income rate.

Because her RMD is smaller than feared, the dollar amount layered on top of her Social Security is smaller too. That keeps a larger slice of her benefit out of the taxable column. The same logic applies to Medicare. Lower forced income reduces the chance of crossing into a higher Income-Related Monthly Adjustment Amount (IRMAA) tier, which would raise her Part B and Part D premiums two years later.

The RMD itself is fully taxable as ordinary income, and it can still pull some additional Social Security into the taxable zone. The divisor’s design caps how aggressive that effect can get in any single year.

The COLA Effect

The 2026 cost-of-living adjustment (COLA) of 2.8% raised her gross Social Security income before any of this tax calculation happens. That bump matters because the income thresholds for taxing Social Security are not indexed to inflation. Every COLA pushes more dollars of benefit into the taxable zone over time, regardless of what her IRA is doing.

A qualified charitable distribution lets her send part of her RMD directly from the IRA to a qualifying charity, and the transferred amount never shows up in her adjusted gross income. For a retiree who already gives to her church or a cause she cares about, that move can shrink the tax torpedo without requiring her to give more than she already planned to.

What Actually Matters

Two points are worth holding onto:

  1. The IRS designed the table to preserve the account. The Uniform Lifetime Table is calibrated to leave most retirees with a balance well into their 90s. The first-year required percentage is small enough that her IRA can keep growing if her investments cooperate.
  2. The tax effect on her Social Security is bounded by the size of the RMD. Because the required amount is modest, the share of her benefit pulled into taxable territory is modest too. Up to 85% can be taxed in extreme cases, but most retirees at her income level land well below that ceiling.

The mistake hardest to undo is panic-selling assets inside the IRA or withdrawing far more than required because the rules felt threatening. RMD age stays at 73 for those born between 1951 and 1959, and 75 for anyone born in 1960 or later, so the timing rules will vary for friends and siblings who ask. A short conversation with a tax preparer who has seen this scenario before can settle the rest.

Contact [email protected] for any questions or corrections.

Originally Appeared Here

Filed Under: Income Tax News

Inside the $900,000 Greek Island Retirement Drawing Americans at 62

June 30, 2026 by

Quick Read

  • Buying a Greek island home outright at €140,000 leaves $600,000 to fund a $47,000 annual budget at a 3.5% withdrawal rate.

  • Staggered Social Security claiming cuts the portfolio’s required annual draw to just $11,000, with a $150,000 treasury bridge covering ages 62 to 67.

  • Greece’s 7% flat tax on foreign income rarely eliminates US tax obligations, since Americans still owe on worldwide income under the US-Greece treaty.

  • Are you ahead, or behind on retirement? SmartAsset’s free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don’t waste another minute; learn more here.

A whitewashed house overlooking the Aegean sounds like a fantasy retirement. Yet for some Americans, a Greek island can be less expensive than coastal California or the Florida Keys. The math can work, but it depends on a handful of factors that most retirement rankings barely mention.

What $900,000 actually buys on a Greek island

Most of the day-to-day expenses in Greece will ultimately be paid in euros, but American retirees typically continue thinking about their finances in dollars because their portfolios, Social Security benefits, and tax obligations remain dollar-based. For that reason, this analysis uses estimated U.S. dollar figures throughout, while recognizing that exchange-rate movements will affect real purchasing power over time.

Living costs vary significantly by island. On lesser-known destinations such as Naxos, Syros, Lefkada, or parts of eastern Crete, an older two-bedroom home in walkable condition can often be found for roughly $100,000 to $200,000. A couple purchasing a home outright for about $160,000 would still have roughly $740,000 of a $900,000 nest egg available for investment and future spending. Property taxes, insurance, municipal fees, and maintenance are generally modest by U.S. standards but should still be budgeted carefully.

Are you ahead, or behind on retirement? SmartAsset’s free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don’t waste another minute; learn more here.

A working annual budget for the couple might include roughly $4,500 for housing carrying costs, $7,800 for groceries and household spending, $2,400 for utilities and internet, $4,800 for transportation, $4,800 for dining and entertainment, $5,000 for annual travel back to the United States, $9,600 for private health insurance, $4,000 for property and miscellaneous reserves, and about $4,500 for taxes. That totals roughly $47,000 per year.

Turning that budget into a portfolio target

Social Security is what makes this scenario practical for many Americans. A couple receiving roughly $36,000 a year in combined benefits covers most of the estimated $47,000 annual budget. That leaves the portfolio responsible for only a relatively modest share of total spending, allowing the investment assets to serve more as a supplement than as the primary source of retirement income.

Subtract a delayed-claim Social Security stream of roughly $36,000 from a $47,000 budget and the portfolio only needs to cover an $11,000 gap once both benefits flow. From 62 to 67, the gap is the full $47,000 minus one early benefit of $17,400, or roughly $30,000 a year for five years. At a 3.5% withdrawal rate appropriate to a 30-plus year horizon, the steady-state $11,000 gap implies a portfolio target of about $315,000. The bridge years require an additional cash bucket of roughly $150,000 in a treasury ladder or short-duration bond fund, with the 10-year Treasury at 4.51% making that ladder genuinely productive. The remaining balance, after the house and the bridge, comfortably funds a diversified mix of index funds and dividend ETFs that compounds across the next three decades.

The Greek tax structure most people get wrong

Greece offers a special tax regime that may allow qualifying foreign retirees to pay a flat 7% tax on certain foreign-source income for up to 15 years. The rules are detailed, subject to change, and depend on establishing Greek tax residency. Americans should remember that U.S. citizens remain subject to U.S. taxation regardless of where they live, making professional cross-border tax advice particularly valuable before relocating.

Currency exposure is the other quiet risk. Because most expenses are paid in euros while most American retirees receive income and hold investments in dollars, exchange-rate movements directly affect purchasing power. A meaningful move in the euro can change annual living costs by thousands of dollars. Maintaining a cash reserve in euros can help reduce the impact of those swings.

The number that actually makes it work

A Greek island retirement on $900,000 is achievable for many Americans. A paid-off home, Social Security income, and a portfolio large enough to cover a relatively modest spending gap create a surprisingly durable plan. The biggest challenges are not day-to-day living costs but taxes, healthcare logistics, and managing the long-term effects of currency fluctuations between the dollar and the euro.

If You’ve Been Thinking About Retirement, Pay Attention (sponsor)

Retirement planning doesn’t have to feel overwhelming. The key is finding expert guidance, and SmartAsset’s simple quiz makes it easier than ever for you to connect with a vetted financial advisor. Here’s how:

  1. Answer a Few Simple Questions. 

  2. Get Matched with Vetted Advisors 

Why wait? Start building the retirement you’ve always dreamed of. Get started today! (sponsor)

Contact ed*******@*******st.com for any questions or corrections.

Originally Appeared Here

Filed Under: Income Tax News

The IRS loses $1 trillion a year to tax cheats — and Trump’s proposed $250 bill could make it worse

June 27, 2026 by

gettyimage.com/ KENT NISHIMURA

President Trump’s plan for a $250 banknote that features his portrait is controversial for a few reasons.

For starters, federal laws dictate that only deceased individuals (1) can be featured on U.S. currency. In fact, a living individual has not appeared on a U.S. coin or bill since 1866, the year that it was banned.

Must Read

Legislation that would permit Trump’s bill to be produced has languished in Congress since it was introduced in February 2025. Now, nearly 16 months later, senate democrats are asking the Treasury Department’s Office of Inspector General to investigate the spending (2) that’s been devoted to what they’re calling “an illegal $250 bill,” which includes designing a mockup of the banknote.

But a recent episode of NPR’s The Indicator From Planet Money podcast revealed another potentially controversial element of the $250 bill, and it has nothing to do with the president’s portrait.

‘A $250 note would be a gift to criminals’

Wailin Wong, one of the podcast’s hosts, recently sat down with journalist and economic commentator Paddy Hirsch, who’s the editor of the podcast. After briefly touching on the opposition and controversy surrounding Trump’s proposed banknote, the two introduced the episode’s theme (3).

“There’s one area of opposition that hasn’t received much attention, the idea that a $250 note would be a gift to criminals,” said Wong.

“Drug dealers, arms smugglers, people traffickers, money launderers — they all love to use large-denomination notes,” added Hirsch.

But before diving into that, the two discussed how the American people don’t often use cash, as this form of payment represented just 14% of U.S. consumer transactions (4) in 2024.

The hosts then shifted their attention to the $100 bill, the largest denomination that America currently produces with nearly 20 billion notes currently in circulation (5). However, Wong was quick to note that the Federal Reserve estimates the majority of $100 notes in circulation are currently held outside the U.S (6).

“So if Americans aren’t using them, who is?” asked Wong. Oliver Bullough, a writer who focuses on financial crimes, offered his two cents on the podcast.

Story Continues

“Why is there so much demand for cash money, despite the fact that ordinary people aren’t using it, is something that I think is explainable, essentially, entirely by its use by criminals,” said Bullough. “The only real, useful purpose for a high-denomination bill is if you want to move a lot of value in a small space at one time, and the only people that want to do that, really, are criminals.”

With this in mind, Hirsch noted that governments around the world are aware of the criminal usage of large banknotes and many are scaling back on producing them. Europe stopped producing its 500-euro note back in 2019, while Singapore stopped printing its 10,000-dollar note back in 2014.

Wong also noted that the U.S. $100 bill is still very popular among criminals despite the rise of cryptocurrency. “That’s because there’s no blockchain attached to a $100 bill, which makes cash even more anonymous than crypto,” she said.

While the hosts made a strong case for the criminal usage of large banknotes, there’s one specific type of criminal they believe could really benefit from a potential $250 bill.

Don’t Miss: Paying too much for car insurance? 3 clever (and free) ways to slash your bill today

‘Tax dodgers love them, too’

As the New York Times reported in 2021, the IRS estimates it loses around $1 trillion every year to tax evasion (7). “We lose way more money from tax evasion each year than we make from printing new currency,” said Hirsch.

Ken Rogoff, former chief economist at the International Monetary Fund who contributed to this episode of the podcast, believes many who use $100 banknotes are either not paying their taxes or aren’t paying as much as they should.

“That’s right,” Wong confirmed. “It’s not just drug dealers and money launderers who like big notes. Tax dodgers love them, too.”

As Wong noted, a $250 banknote could make it a lot easier for people to dodge taxes “simply because cash transactions are easy to make anonymous, and it’s a lot easier to transact in cash if you’re using large notes.”

Rogoff also believes tax collections would increase if America were to stop printing large denominations, which is why he doesn’t have much faith in Trump’s $250 banknote coming to fruition.

“Ken [Rogoff] doesn’t believe this note will come to pass, for a variety of reasons,” said Hirsch. “But if it did, he says, the government would end up losing a whole lot of tax money on the deal, and that would be really bad for America.”

You May Also Like

Join 250,000+ readers and get Moneywise’s best stories and exclusive interviews first — clear insights curated and delivered weekly. Subscribe now.

Article Sources

We rely only on vetted sources and credible third-party reporting. For details, see our ethics and guidelines.

Washingtonpost (1); Axios (2); Npr (3); Finextra (4); Investopedia (5); Chicagofed (6); Nytimes (7)

This article originally appeared on Moneywise.com under the title: The IRS loses $1 trillion a year to tax cheats — and Trump’s proposed $250 bill could make it worse

This article provides information only and should not be construed as advice. It is provided without warranty of any kind.

Originally Appeared Here

Filed Under: Income Tax News

We Can’t Address the U.S. Deficit Without Corporate Tax Reform

June 24, 2026 by

It’s no secret that the U.S. public debt is out of control. It recently surpassed the size of the U.S. economy for the first time since World War II, and is slated to get even worse in the coming years. A recent Congressional Budget Office (CBO) report projects that public debt will reach a record 120 percent of Gross Domestic Product (GDP) by 2036, largely driven by successive rounds of federal tax cuts implemented over the past three decades. A broader fiscal course correction – one that raises new revenues and improves efficiency in government spending without harming the nation’s most vulnerable citizens – is desperately needed.

While lawmakers on both sides of the aisle have been sounding the alarm for decades, they have largely ignored a major contributing cause of our nation’s skyrocketing debt: declining corporate tax revenues. Congress has allowed corporate taxes as a share of total revenues to drop from over 30 percent during the 1950s to just 7 percent as of 2022. This decline is the result of successive rounds of lavish tax handouts to large corporations, including, most recently, around $1 trillion in tax breaks that were expanded and made permanent by lawmakers in 2025. Congress did so at the expense of the American public and their constituents: polling shows that more than four out of five midterm voters, including 67 percent of Trump voters, support raising taxes on large corporations.

This story should not be surprising. The statutory corporate income tax rate has been cut by more than half since its peak in the 1960s to just 21 percent. Effective corporate tax rates, however, are substantially lower than the already historically low statutory rate. Analysis by the Government Accountability Office has shown that the average corporate effective tax rate plummeted to just 9 percent after the 2017 tax reform went into effect. Post-2025, marginal effective rates are expected to decline even more precipitously.

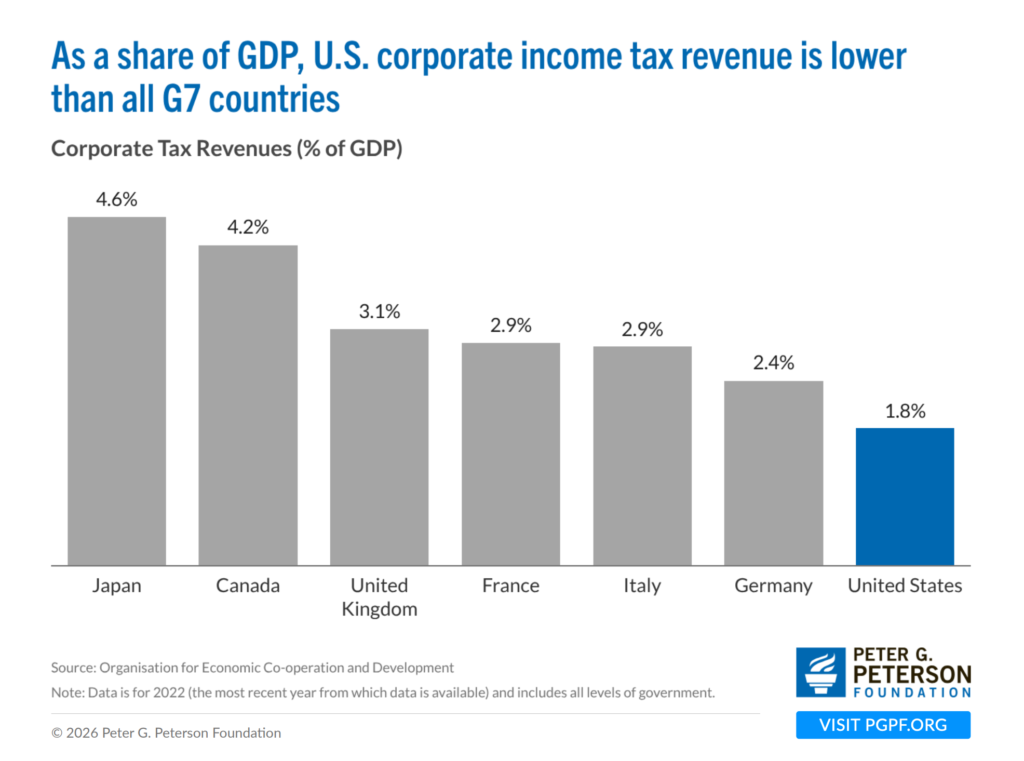
The U.S. also collects less corporate tax than other developed countries as a percentage of overall tax revenues. OECD countries collect an average of 12 percent of revenues in the form of corporate income taxes, while the U.S. collects just 7 percent of revenues from corporate income taxes.

We Can’t Address the U.S. Deficit Without Corporate Tax Reform

This trend will only worsen in the coming years. While the 2025 tax reform didn’t change the statutory corporate income tax rate, it included costly international business provisions on top of dramatic expansions of corporate tax breaks like bonus depreciation and deductions for interest expenses, which will lower the effective tax rates multinational corporations pay. Congress’ longstanding failure to adequately tax the foreign profits of the nation’s largest companies doesn’t just cost the U.S. revenues: it also incentivizes the continued movement of investment and income abroad. This means fewer jobs for Americans, fewer dollars in our economy, and an uneven playing field that puts American entrepreneurs and small businesses at a disadvantage.

Commonsense reforms popular among voters of both parties could help reverse the trend of declining U.S. corporate revenues. First, Congress should equalize the tax rates that corporations pay on income earned abroad and at home, repealing the large tax discount for foreign income that companies have used to shrink their tax bills through the elaborate offshore structures. Second, Congress should get rid of wasteful tax breaks like the foreign-derived deduction-eligible income (FDDEI, formerly FDII) deduction, which rewards firms for profitable export activity they likely would have engaged in anyway.

But big corporations aren’t just shifting profits to tax havens: in many cases, they’re opting not to be taxed as corporations at all. A growing number of businesses are not taxed separately as corporate entities, but merely “pass through” their obligations to their owners. Once the domain of small businesses, these entities are increasingly large and complex, including many private equity and hedge funds, and are the vehicles by which many wealthy Americans hold their wealth in offshore tax havens. Pass-throughs earn more than half of all U.S. business income. The size and complexity of many of these businesses make them essentially un-auditable; the IRS examination rate for complex partnerships has collapsed to less than 0.1 percent in 2023.

To address these imbalances, Congress should pursue broad reforms to tax the largest pass-through businesses as corporations and make sure that the IRS has the resources necessary to effectively audit large, complex businesses, including both multinational corporations and pass-throughs. The IRS must also be well-resourced to pursue offshore tax evasion by wealthy American individuals, which runs into the billions of dollars in fines alone, even before considering back taxes.   

There is no one magic bullet to address our nation’s runaway debt. Congress will need to make hard choices to both raise new revenue and improve the efficiency of federal spending. The problem will prove impossible to address, however, so long as the nation’s largest and most successful businesses continue to avoid paying meaningful levels of tax. Plenty of policymakers pay lip service to “fiscal responsibility” when it is politically convenient – if they want to prove that they are serious about tackling our fiscal crisis, then corporate tax reform should be at the top of the agenda.

Originally Appeared Here

Filed Under: Income Tax News

Your Dividend Portfolio Says $150,000. The IRS Says Something Else

June 21, 2026 by

© J.J. Gouin / Shutterstock.com

Generating $150,000 a year from dividends and distributions is an accomplishment. What matters next is how much of that income survives taxation. Two retirees can report the same portfolio income and end up with very different amounts available to spend simply because their income is taxed differently.

To illustrate the point, consider three portfolios that each generate $150,000 of annual income. The examples below assume a single filer claiming the 2026 standard deduction of $16,100 and receiving no other income.

Scenario one: mostly qualified dividends

A portfolio concentrated in large-cap dividend stocks, dividend-growth funds, and other investments that generate primarily qualified dividends benefits from the federal long-term capital gains tax structure. After the standard deduction, taxable income falls to roughly $133,900. A portion of that income qualifies for the 0% rate, while the remainder is taxed at 15%.

The result is a federal tax bill of approximately $12,800, leaving about $137,200 of after-tax income. For a six-figure income stream, the effective federal tax rate remains surprisingly low. That favorable treatment is one of the biggest advantages qualified dividends offer income-focused investors.

Scenario two: a mixed portfolio

Now assume the portfolio produces half of its income from qualified dividends and half from ordinary-income sources such as non-qualified REIT distributions, bond interest, business development company dividends, and certain partnership distributions. The qualified portion continues to benefit from lower tax rates, while the ordinary-income portion moves through the standard federal tax brackets.

Under that structure, the federal tax bill rises to roughly $18,900, reducing after-tax income to about $131,100. The portfolio generates exactly the same $150,000 on paper, yet the investor keeps about $6,000 less each year. The brokerage statement looks identical. The tax return does not.

Scenario three: high-yield ordinary income

Now build the $150,000 from covered-call ETFs taxed as ordinary income, mortgage REITs, high-yield bond funds, and BDCs. Almost everything is taxed at ordinary rates. After the standard deduction, the income climbs all the way into the 24% bracket, which starts at $105,700.

Federal tax bill: about $24,700. Net federal income: roughly $125,300. The aggressive yield strategy that looked best on paper hands back almost $12,000 more in federal tax every year than the qualified-dividend version.

State tax stacks on top

States treat dividends differently. Florida, Texas, Tennessee, and a handful of others charge nothing. California treats every dollar of qualified and ordinary dividend income the same and taxes it at marginal rates that reach into the 9.3% bracket at this income level. New York, New Jersey, and Oregon land in similar territory. A California retiree pulling $150,000 from the high-yield portfolio can lose another roughly $9,000 to $11,000 on top of federal, pushing net income closer to $115,000.

Asset location does the heavy lifting

Where the income is generated matters as much as what generates it.

  1. Taxable brokerage: the right home for qualified dividends and tax-efficient equity funds. The 15% rate is hard to beat, and qualified income keeps the effective rate low. Holding a high-yield bond fund or covered-call ETF here is the most expensive choice possible.
  2. Traditional IRA or 401(k): the right home for ordinary-income generators. REITs, BDCs, high-yield bonds, and option-income ETFs all distribute at ordinary rates anyway, so sheltering them defers the tax and lets the compounding run untouched. Withdrawals then come out at whatever bracket applies in retirement.
  3. Roth IRA: the right home for the highest-growth, highest-yield positions a retiree plans to hold for decades. Every dollar of distribution and appreciation is tax-free after the five-year rule is satisfied, which is why Suze Orman calls it “the best retirement account you are ever going to have, bar none”.

A retiree with all three account types can route the same $150,000 of gross income and keep noticeably more of it simply by moving the right asset to the right wrapper.

Now what?

Pull last year’s 1099-DIV and check Box 1a against Box 1b. The ratio of ordinary to qualified dividends is the single biggest driver of the tax bill, and most investors have never looked. Then map each income-producing holding to the account it sits in and ask whether the ordinary-income payers belong in the IRA instead of the brokerage. With the 10-year Treasury near 4.5%, the after-tax yield comparison between a qualified-dividend equity portfolio and a taxable bond ladder is closer than it looks. Run the math on your actual bracket before assuming higher yield means higher income.

Originally Appeared Here

Filed Under: Income Tax News

SJC cites ‘misleading summary’ by AG Campbell in striking down ballot initiative to lower state income tax

June 18, 2026 by

The Massachusetts Supreme Judicial Court (SJC) struck down an initiative petition to lower the state income tax from 5% to 4%, stating that a summary of the proposal authored by the Attorney General’s office and used to collect required signatures was misleading and must be disqualified from appearing on the ballot.

The high court ruled in favor of eight Massachusetts voters who challenged AG Andrea Campbell’s summary of the Initiative Petition 25-18, title “[An] Initiative Petition for a Law Relative to Reducing the State Personal Income Tax Rate from 5% to 4%,” arguing that she did not provide a “fair, concise summary” of the proposed law as required by state law.

The proposal would have gradually reduced the state income tax rate from 5% to 4% over three years, starting at 4.67% in 2027, then lowered to 4.33% in 2028, and then finally 4.00% in 2029.

Specifically, the court agreed with the interveners that Campbell falsely stated in her summary that the proposed law would not lower the tax rate on long-term capital gains, when in fact, as written, it would lower it.

“The challenged language states the petition would “lower the tax rates on (1) personal taxable income consisting of interest and dividends, and (2) personal taxable income other than interest, dividends or capital gain income, such as wages and salaries” (emphases added). According to plaintiffs, the emphasized exclusion tells voters the long-term capital gain tax rate will remain unchanged. Under current law, the petition would in fact lower it,” said Associate Justice Serges Georges in his decision.

“We agree; the summary misstates the petition’s impact. As written, the proposed law would reduce the tax rate for Part B taxable income, including income derived from wages and salaries. Because current law ties the tax rate for most Part B taxable income, i.e., long-term capital gain income, to the Part B rate, the proposed law also would reduce the long-term capital gain tax rate,” he said.

The petition was originally filed with Campbell’s office by ten registered Massachusetts voters in August 2025, which was then certified and sent to the Secretary of State’s Office in September. Campbell’s summary was then placed in the forms used to collect signatures in order to certify the petition for the ballot.

“This proposed law would, over a period of three years, lower the tax rates on (1) personal taxable income consisting of interest and dividends, and (2) personal taxable income other than interest, dividends or capital gain income, such as wages and salaries,” Campbell’s summary stated incorrectly states. “Both tax rates were 5.00% for tax year 2024. The proposed law would set both tax rates at 4.67% for tax year 2027, 4.33% for tax year 2028, and 4.00% beginning in tax year 2029.”

Proponents of the measure collected and submitted to the Secretary of State over 85,000 signatures to qualify for the ballot by December.

Fiscal watchdogs like the Pioneer Institute and the Massachusetts Fiscal Alliance slammed decision as well as Campbell for the misleading summary that resulted in the disqualification of the petition.

“This is a disgraceful outcome for Massachusetts taxpayers and a direct result of the Attorney General’s failure to do her job properly. More than 100,000 residents signed petitions to put tax relief before the voters. They followed the process, did the work, and earned a place on the ballot,” MassFiscal Executive Director Paul Craney said in a written statement.

“The SJC did not reject the tax cut on the merits. The court did not say taxpayers were wrong to want relief. The court removed this question because the Attorney General’s summary failed to meet the constitutional standard required for ballot petitions. That is an extraordinary failure by an office that has enormous responsibility over the initiative petition process,” Craney continued.

The Pioneer Institute for Public Policy Research is calling the SJC ruling a “serious disappointment,” pointing to Massachusetts remaining as one of the highest tax and cost burden states in the U.S. while also seeing some of the highest outmigration rates in the country.

“The Court’s decision rests on a drafting error in the Attorney General’s summary of the petition—a matter entirely outside the control of voters and petition signers. As a result, the people of Massachusetts will be denied the opportunity to decide whether the Commonwealth should reduce the income tax rate from 5 percent to 4 percent,” the Pioneer Institute said in a statement.

“No ballot question has ever been removed due to a minor drafting mistake.  Today’s decision means that a technical defect in a summary prepared by the government can prevent voters from considering a question that otherwise qualified for the ballot,” it said.

Campbell’s office responded with a statement: “We respect the SJC’s decision and will continue to work diligently to ensure that ballot initiatives are summarized fairly and transparently.”

Since 2020, Massachusetts has seen a net domestic outmigration of 182,000 residents, particularly between the ages of 26 and 34, the Pioneer Institute says. This as Massachusetts continues to experience declining job growth, joining only a handful of other states that has continued to lose jobs since the end of the COVID pandemic.

The push to lower the state’s income tax rate has seen positive reaction amongst Bay State voters in recent polls, but has been criticized as a “gimmick” by Beacon Hill leadership, including the likes of Gov. Maura Healey, Senate President Karen Spilka and House Speaker Ron Mariano.

“Neither the Attorney General’s nor the interveners’ arguments persuade us. The summary tells voters that the proposed law would “lower the tax rates on . . . personal taxable income other than . . . capital gain income.” In ordinary English, “other than” means “except for” or “besides,” Justice Georges said.

Originally Appeared Here

Filed Under: Income Tax News

Monday Morning Accounting News Brief: Oh Rats! The IRS Is Infested; PwC Partners Will Divorce If It Spares Their Cash | 6.15.26

June 15, 2026 by

Good morning, capital markets servants. Everyone have a good weekend? Good. Got some news for you.

Here’s a heckuva headline to start things off: IRS employees protest rat infestation at Chamblee campus; agency announces telework option: “We looked at each other. It screamed, I screamed.”

Several employees at the Internal Revenue Service’s Atlanta campus in Chamblee say they are frustrated with what they describe as ongoing rodent infestations and deteriorating working conditions inside the facility.

Current and former employees, along with union representatives, gathered outside the campus Thursday afternoon to protest the conditions and call for expanded remote work options.

Some current employees told CBS News Atlanta they did not attend the demonstration because they feared retaliation from management.

Thank you, NTEU Chapter 284 for speaking out about the unsafe working conditions at the IRS Atlanta Campus. IRS has now announced they will allow some employees to telework, but we’ll keep making our voices heard until ALL employees have a safe workplace: https://t.co/tk3813Hr45 pic.twitter.com/DSH5XEjMyJ

— NTEU News (@NTEUNews) June 12, 2026

Hey that rat looks familiar…

The IRS Phone Bank Pays HOW Much!?

In other IRS news, the inspector general has issued an unsurprising report that says skilled employees were slumming it on low level work while still pulling their skilled salaries:

Still other employees were “involuntarily detailed” to other jobs within the agency, including supervisors and high-skilled techs who make $100,000 or more, but were pressed into duty answering the phones — a job that can pay as little as $35,000.

They’re still getting paid their full salary and benefits, however, the inspector general said.

“Positions at these grade levels often include senior, supervisory, and highly specialized technical employees. However, the positions to which they are detailed are at lower GS grade levels,” the report said.

Can we talk about how they’re paying $35,000 to answer phones or nah?

Getting Divorced Over an Audit Failure

As you may have heard, PwC is going to have to pay a pound of flesh for Evergrande. And some partners are taking drastic measures to protect their wealth:

The liquidation of China Evergrande Group, the collapsed property developer, is raising concerns among some partners at its former auditor PricewaterhouseCoopers China about the potential impact on their own finances.

Several partners at PwC’s Hong Kong and mainland China affiliates say they are exploring strategies to safeguard personal assets, in case legal and regulatory challenges facing the firms ever spill over into any financial or legal burdens for themselves. One says he has even contemplated divorce as a means to shield wealth, while another is cutting education budgets for his children.

For Those Who Like Tax Policy

ICYMI: Deloitte published their 2026 Global Tax Policy Survey, a survey of 1,010 tax and finance leaders across 28 jurisdictions. A takeaway:

A majority of respondents (85%) now expect AI-based tax compliance software to deliver positive impacts ranging from improved accuracy to reduced compliance costs, while 15% remain more negative, expecting the main impact to be increased implementation costs.

When it comes to the question “What is the biggest challenge for tax leaders in 2026?” Deloitte says:

The biggest challenge comes from the rising tide of complexity in the tax system. While some of it can be attributed to sources such as Pillar Two and the EU Carbon Border Adjustment Mechanism, a lot of complexity also comes from inconsistent domestic implementation of international regimes. The volume of public tax transparency disclosures stemming from a combination of regulatory requirements and voluntary disclosures, adds further pressure and is expected to increase in coming years.

EY Doesn’t Want Companies to Focus Solely on AI Cost-Cutting

A Business Insider article that sounds like a pitch for EY’s AI services more than anything: EY’s AI leader says companies are too focused on AI cost-cutting

Wall Street tends to reward CEOs who slash jobs in the name of efficiency.

However, those companies are leaning into an area with the “smallest level of return,” Dan Diasio, EY’s global consulting AI leader, told Business Insider.

“There’s a very clear limit to the amount of value you can create by just focusing on productivity and cost reduction,” said Diasio, who also serves as EY’s Americas consulting CTO.

He said AI may be able to shrink the time spent on a task, but it doesn’t necessarily eliminate the job around it. If cost reduction is the main strategy, those companies are effectively asking AI to pay for itself by reducing headcount.

Meanwhile, AFR published this: How AI threatens the giants of consulting

God Forbid We Train Anyone Anymore

Over at PwC, they analyzed global job ads and found employers want senior-level skills even in newbies:

Employers in AI-exposed fields are increasingly looking for entry-level workers to have the skills that they previously expected from senior workers, including emotional intelligence, judgment, and leadership.

The findings come from PwC’s 2026 AI jobs barometer, released on June 15th, which analyzed over 1 billion job advertisements globally.

Analysis of 2.4 million entry-level roles in the US found that AI-exposed roles are seven times more likely to list “traditionally senior” skills than they were in 2019.

The skills now expected of less experienced staff include motivational leadership, team building, people and stakeholder management, process management, mentorship, and data-driven decision-making.

PwC themselves lists some of these qualities as desirable in candidates:

We need you to lead yourself and others, regardless of your grade, by making a real difference in the work you do. This means delivering results in a responsible, authentic, resilient, inclusive and passionate way.

  • Do you learn from your opportunities and take the time to develop your personal approach to work?
  • Do you lead others to be the best they can be, whether you’re part of a team or leading one?
  • Do you act with integrity and uphold professional standards at all times?

Let’s wrap this up here. If you have a tip or story for us, please feel free to reach out via email or text anytime. Have a great week!


Originally Appeared Here

Filed Under: Income Tax News

Judge extends block on $1.8B Trump ‘Anti-Weaponization Fund’

June 12, 2026 by

ALEXANDRIA, Va. (AP) — A federal judge agreed on Friday to extend a court-ordered block on the Trump administration’s creation and operation of a $1.8 billion settlement fund for compensating people who claim to be victims of a weaponized government.

Earlier this month, acting Attorney General Todd Blanche told Congress that the government is scrapping its plans for the fund in the face of a fierce bipartisan backlash, and government attorneys have argued that lawsuits challenging the fund are now moot. But plaintiffs’ attorneys aren’t satisfied by Blanche’s assurances that the fund won’t move forward.

Neither was U.S. District Judge Leonie Brinkema, who ruled that the “Anti-Weaponization Fund” will remain blocked until further notice from the court.

“The (government’s) mootness argument, in my view, doesn’t go anywhere,” the judge said.

President Donald Trump, meanwhile, has not publicly and unequivocally endorsed the fund’s cancellation. He has continued to express support for it in remarks to reporters.

Brinkema gave the parties a week to negotiate an agreement for Trump administration officials, including Blanche, to submit a sworn declaration that the administration won’t revive the fund.

Brinkema previously agreed to temporarily block the administration from proceeding with the fund for at least two weeks. Her May 29 order was due to expire on Friday.

Trump’s Republican administration created the fund to resolve his lawsuit against the Internal Revenue Service over the leak of his tax returns.

Plaintiffs who sued to block fund payouts argue that the government can’t legally divert taxpayer money into what they argue is a slush fund for compensating Trump’s allies.

In a separate case on Wednesday, a different judge in Washington, D.C., rejected a government watchdog’s parallel request for a court order temporarily blocking the Trump administration from forging ahead with the fund. U.S. District Judge Richard Leon said he accepts Blanche’s representation that the fund is now moot.

Leon had asked Justice Department attorney Andrew Block why Blanche doesn’t formally rescind his May 18 order establishing the fund. Block said he didn’t know. He still didn’t have an answer to that question when Brinkema posed it two days later.

“It’s a huge gap in the record that we don’t have an answer to that question,” said Brinkema, who was nominated to the bench by President Bill Clinton, a Democrat.

Block said he couldn’t provide her with a “concrete answer” because he doesn’t have direct access to Blanche.

“All I would be doing is speculating,” he told the judge.

In the Virginia case, attorneys from the legal advocacy group Democracy Forward asked for an order to temporarily suspend the fund’s implementation and stop the Trump administration from disbursing any payouts from it.

The plaintiffs include a fired prosecutor and a college professor acquitted of assaulting federal agents at a protest. Also named as plaintiffs are the government watchdog Common Cause; the city of New Haven, Connecticut; and the National Abortion Federation, an association of abortion providers.

Even before the Trump administration said it was dropping the fund, the Justice Department did not form the five-member commission that would decide on payout criteria, so no money was paid out nor claims accepted.

Many of the Republican president’s allies are opposed to compensating rioters who stormed the U.S. Capitol on Jan. 6, 2021, after he lost the 2020 presidential election to Democrat Joe Biden. In May, however, Blanche wouldn’t rule out the possibility that Capitol rioters could be eligible to apply for payments from the fund.

Trump issued mass pardons to Capitol rioters on his first day back in the White House last year. More than 1,500 people were charged in the Jan. 6 attack before Trump erased every case with his sweeping act of clemency.

Democracy Forward attorney Pooja Boisture said reviving the fund would irreparably harm the lawsuit’s plaintiffs. A court order to block it wouldn’t harm the government if the administration is truly abandoning it, as Blanche testified, Boisture told the judge, who agreed with that argument.

Originally Appeared Here

Filed Under: Income Tax News

Missouri parks and soils sales tax up for renewal in August

June 9, 2026 by

State

AlabamaAlaskaArizonaArkansasCaliforniaColoradoConnecticutDelawareFloridaGeorgiaHawaiiIdahoIllinoisIndianaIowaKansasKentuckyLouisianaMaineMarylandMassachusettsMichiganMinnesotaMississippiMissouriMontanaNebraskaNevadaNew HampshireNew JerseyNew MexicoNew YorkNorth CarolinaNorth DakotaOhioOklahomaOregonPennsylvaniaRhode IslandSouth CarolinaSouth DakotaTennesseeTexasUtahVermontVirginiaWashingtonWashington D.C.West VirginiaWisconsinWyomingPuerto RicoUS Virgin IslandsArmed Forces AmericasArmed Forces PacificArmed Forces EuropeNorthern Mariana IslandsMarshall IslandsAmerican SamoaFederated States of MicronesiaGuamPalauAlberta, CanadaBritish Columbia, CanadaManitoba, CanadaNew Brunswick, CanadaNewfoundland, CanadaNova Scotia, CanadaNorthwest Territories, CanadaNunavut, CanadaOntario, CanadaPrince Edward Island, CanadaQuebec, CanadaSaskatchewan, CanadaYukon Territory, Canada

Zip Code

Country

United States of AmericaUS Virgin IslandsUnited States Minor Outlying IslandsCanadaMexico, United Mexican StatesBahamas, Commonwealth of theCuba, Republic ofDominican RepublicHaiti, Republic ofJamaicaAfghanistanAlbania, People’s Socialist Republic ofAlgeria, People’s Democratic Republic ofAmerican SamoaAndorra, Principality ofAngola, Republic ofAnguillaAntarctica (the territory South of 60 deg S)Antigua and BarbudaArgentina, Argentine RepublicArmeniaArubaAustralia, Commonwealth ofAustria, Republic ofAzerbaijan, Republic ofBahrain, Kingdom ofBangladesh, People’s Republic ofBarbadosBelarusBelgium, Kingdom ofBelizeBenin, People’s Republic ofBermudaBhutan, Kingdom ofBolivia, Republic ofBosnia and HerzegovinaBotswana, Republic ofBouvet Island (Bouvetoya)Brazil, Federative Republic ofBritish Indian Ocean Territory (Chagos Archipelago)British Virgin IslandsBrunei DarussalamBulgaria, People’s Republic ofBurkina FasoBurundi, Republic ofCambodia, Kingdom ofCameroon, United Republic ofCape Verde, Republic ofCayman IslandsCentral African RepublicChad, Republic ofChile, Republic ofChina, People’s Republic ofChristmas IslandCocos (Keeling) IslandsColombia, Republic ofComoros, Union of theCongo, Democratic Republic ofCongo, People’s Republic ofCook IslandsCosta Rica, Republic ofCote D’Ivoire, Ivory Coast, Republic of theCyprus, Republic ofCzech RepublicDenmark, Kingdom ofDjibouti, Republic ofDominica, Commonwealth ofEcuador, Republic ofEgypt, Arab Republic ofEl Salvador, Republic ofEquatorial Guinea, Republic ofEritreaEstoniaEthiopiaFaeroe IslandsFalkland Islands (Malvinas)Fiji, Republic of the Fiji IslandsFinland, Republic ofFrance, French RepublicFrench GuianaFrench PolynesiaFrench Southern TerritoriesGabon, Gabonese RepublicGambia, Republic of theGeorgiaGermanyGhana, Republic ofGibraltarGreece, Hellenic RepublicGreenlandGrenadaGuadaloupeGuamGuatemala, Republic ofGuinea, Revolutionary
People’s Rep’c ofGuinea-Bissau, Republic ofGuyana, Republic ofHeard and McDonald IslandsHoly See (Vatican City State)Honduras, Republic ofHong Kong, Special Administrative Region of ChinaHrvatska (Croatia)Hungary, Hungarian People’s RepublicIceland, Republic ofIndia, Republic ofIndonesia, Republic ofIran, Islamic Republic ofIraq, Republic ofIrelandIsrael, State ofItaly, Italian RepublicJapanJordan, Hashemite Kingdom ofKazakhstan, Republic ofKenya, Republic ofKiribati, Republic ofKorea, Democratic People’s Republic ofKorea, Republic ofKuwait, State ofKyrgyz RepublicLao People’s Democratic RepublicLatviaLebanon, Lebanese RepublicLesotho, Kingdom ofLiberia, Republic ofLibyan Arab JamahiriyaLiechtenstein, Principality ofLithuaniaLuxembourg, Grand Duchy ofMacao, Special Administrative Region of ChinaMacedonia, the former Yugoslav Republic ofMadagascar, Republic ofMalawi, Republic ofMalaysiaMaldives, Republic ofMali, Republic ofMalta, Republic ofMarshall IslandsMartiniqueMauritania, Islamic Republic ofMauritiusMayotteMicronesia, Federated States ofMoldova, Republic ofMonaco, Principality ofMongolia, Mongolian People’s RepublicMontserratMorocco, Kingdom ofMozambique, People’s Republic ofMyanmarNamibiaNauru, Republic ofNepal, Kingdom ofNetherlands AntillesNetherlands, Kingdom of theNew CaledoniaNew ZealandNicaragua, Republic ofNiger, Republic of theNigeria, Federal Republic ofNiue, Republic ofNorfolk IslandNorthern Mariana IslandsNorway, Kingdom ofOman, Sultanate ofPakistan, Islamic Republic ofPalauPalestinian Territory, OccupiedPanama, Republic ofPapua New GuineaParaguay, Republic ofPeru, Republic ofPhilippines, Republic of thePitcairn IslandPoland, Polish People’s RepublicPortugal, Portuguese RepublicPuerto RicoQatar, State ofReunionRomania, Socialist Republic ofRussian FederationRwanda, Rwandese RepublicSamoa, Independent State ofSan Marino, Republic ofSao Tome and Principe, Democratic Republic ofSaudi Arabia, Kingdom ofSenegal, Republic ofSerbia and MontenegroSeychelles, Republic ofSierra Leone, Republic ofSingapore, Republic ofSlovakia (Slovak Republic)SloveniaSolomon IslandsSomalia, Somali RepublicSouth Africa, Republic ofSouth Georgia and the South Sandwich IslandsSpain, Spanish StateSri Lanka, Democratic Socialist Republic ofSt. HelenaSt. Kitts and NevisSt. LuciaSt. Pierre and MiquelonSt. Vincent and the GrenadinesSudan, Democratic Republic of theSuriname, Republic ofSvalbard & Jan Mayen IslandsSwaziland, Kingdom ofSweden, Kingdom ofSwitzerland, Swiss ConfederationSyrian Arab RepublicTaiwan, Province of ChinaTajikistanTanzania, United Republic ofThailand, Kingdom ofTimor-Leste, Democratic Republic ofTogo, Togolese RepublicTokelau (Tokelau Islands)Tonga, Kingdom ofTrinidad and Tobago, Republic ofTunisia, Republic ofTurkey, Republic ofTurkmenistanTurks and Caicos IslandsTuvaluUganda, Republic ofUkraineUnited Arab EmiratesUnited Kingdom of Great Britain & N. IrelandUruguay, Eastern Republic ofUzbekistanVanuatuVenezuela, Bolivarian Republic ofViet Nam, Socialist Republic ofWallis and Futuna IslandsWestern SaharaYemenZambia, Republic ofZimbabwe

Originally Appeared Here

Filed Under: Income Tax News

  • « Go to Previous Page
  • Page 1
  • Page 2
  • Page 3
  • Page 4
  • Interim pages omitted …
  • Page 42
  • Go to Next Page »

Primary Sidebar

More to See

IRS offers guidance on employer credit for paid family and medical leave

IRS offers guidance on employer credit for paid family and medical leave

The Internal Revenue Service and the Treasury Department issued guidance Wednesday on the permanent extension of the employer credit for paid family … [Read More...] about IRS offers guidance on employer credit for paid family and medical leave

Debate over Missouri income tax defines August primary election

Debate over Missouri income tax defines August primary election

State lawmakers are putting the future of Missouri taxation in voter's hands this primary season.Amendment 5, one of four amendments on Tuesday's … [Read More...] about Debate over Missouri income tax defines August primary election

Taxpayers with a history of timely filing and paying can now get automatic penalty relief without requesting it, under a new IRS program.

Taxpayers with a history of timely filing and paying can now get automatic penalty relief without requesting it, under a new IRS program.

The IRS introduced the Automatic Exemption from Penalty on July 8, 2026, a new system that will eliminate the need for eligible taxpayers to request … [Read More...] about Taxpayers with a history of timely filing and paying can now get automatic penalty relief without requesting it, under a new IRS program.

Privacy Policy | Terms and Conditions | About/ Contact
Copyright © 2026 · Income Tax Aid - Lasiter CPAs

Powered by Electric Oak